

Together Loans
by Transform Credit Inc
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
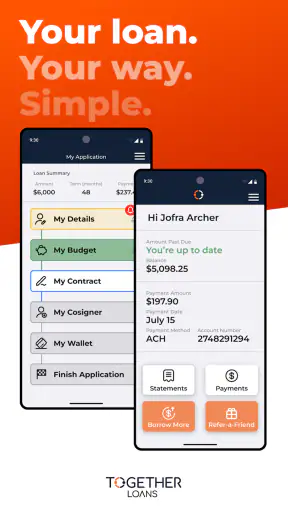
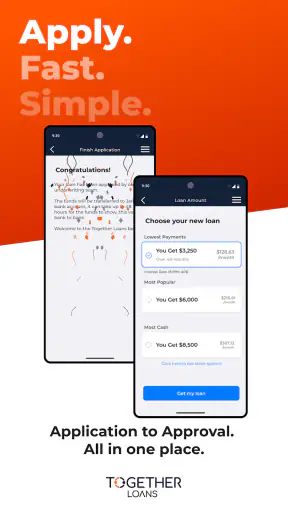
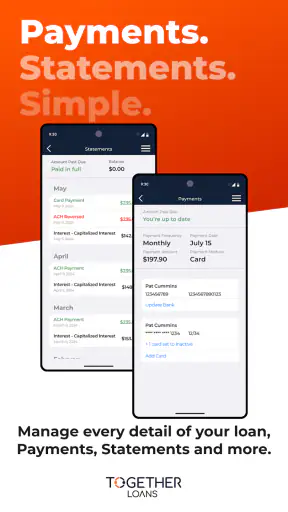
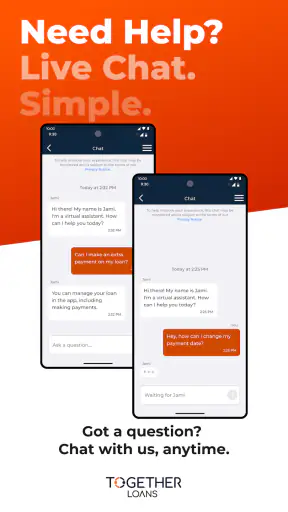
 Analysis by Getfullapps
Managing a loan is rarely something I want to turn into a daily chore. I mainly want a clear place to check what I owe, understand what needs attention, and deal with account tasks without searching through old emails or paperwork. That is the role Together Loans is designed to fill: it is a finance app from Transform Credit Inc for managing a Together Loans account in one place.
My overall impression is that it makes the most sense as a companion to an existing loan relationship, not as a general budgeting app or a complete personal-finance dashboard. It is free to install, carries an Everyone content rating, and has reached over one hundred thousand installs. Its average rating is 4.3 from more than six hundred ratings, which suggests that many users find the focused approach useful, while also leaving room for the occasional account-specific frustration that is common with financial apps.
What the app is really for
The most important thing to understand before installing it is the app’s narrow purpose. Together Loans is not presented as a marketplace for comparing every lender, a banking replacement, or a tool for building a full household budget. Its value comes from putting loan-related information and actions behind one account-focused interface.
That focus can be a genuine advantage. A broad finance app may show spending categories, bank balances, investments, and credit information, but those extra sections can make a simple loan task harder to find. With this app, I would open it when I specifically need to review my Together Loans account rather than when I want a complete picture of my finances.
This distinction also makes the app easier to judge fairly. If you already have a Together Loans account and want a convenient mobile access point, the app has a clear reason to exist. If you are still comparing borrowing options, looking for debt advice, or trying to organize several lenders in one place, it is unlikely to replace the tools you already use.
The first-use experience and account expectations
For a finance app, the first practical question is not whether the design looks attractive. It is whether I can get to the right account safely and understand what I am being asked to do. I would approach setup with the same care I use for any loan service: download the official app, check that the developer name is Transform Credit Inc, and avoid entering account details into an imitation application.
The app’s current version is 9.1.2, and it supports devices running Android 7.0 or later. That makes it accessible on many older Android phones, although compatibility alone does not tell me how well it will feel on every device. I would still keep the operating system updated where possible, particularly when handling financial information.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
One useful habit is to decide what I need before opening the app. If I am checking a payment, I look for the relevant account detail first. If I am reviewing a message or account request, I deal with that before browsing elsewhere. This sounds simple, but it reduces the chance of making a rushed decision after opening a finance app while distracted.
Trust starts with visible account boundaries
I prefer financial apps that make their boundaries obvious. Together Loans is easier to trust when I treat it as an account-management channel rather than as an adviser. That means I use it to review information connected to my loan and to handle the choices the service visibly presents, while keeping independent records for my wider budget.
That separation matters because an account screen can show what is due without showing whether the payment fits comfortably into the rest of my month. I would not use the app alone to decide whether taking on additional debt is sensible. I would compare the loan obligation with rent, utilities, food, and other commitments in a separate budget.
The developer and app identity are also part of that trust check. The listing identifies Transform Credit Inc, and the app is free rather than requiring an upfront purchase. Free access is convenient, but it does not mean borrowing itself is free. I would always read the loan terms and any relevant account information inside the service instead of treating the app’s download price as a statement about the cost of credit.
Controls I would look for during normal use
The strongest reason to use a dedicated loan app is convenience during small but important moments. I might be away from home and need to confirm an account detail, or I might remember a loan task while planning the rest of my month. Having a mobile place for that account can be less stressful than opening a browser, finding a saved message, and trying to remember which page is current.
I would pay particular attention to how clearly the app separates general account information from actions that can affect my finances. A good workflow should make it obvious when I am only viewing a balance or status and when I am submitting a request, changing an arrangement, or confirming something with financial consequences. Whenever a screen asks me to proceed, I would slow down and read the wording rather than tapping through automatically.
Another practical control is keeping notifications purposeful. If the app offers notification choices, I would select only the alerts that help me manage the loan and avoid allowing sensitive details to appear in a lock-screen preview. I would also review the phone’s notification settings after installation. This is not about assuming the app is unsafe; it is about controlling how financial information appears when other people might see the device.
I would use a strong device passcode and avoid managing the account over an unsecured public connection. Those habits are especially worthwhile for a loan app because the risk is not limited to someone seeing a balance. Account access can expose personal information and create confusion about which requests or messages are genuine.
Data-sensitive moments deserve extra attention
Loan management naturally involves sensitive information, so I would treat every sign-in, verification step, message, and account change as a moment to pause. The app should be judged by the choices it visibly gives me, not by assumptions about hidden behavior. I would read any permission request in context and ask whether it is necessary for the task I am trying to complete.
If a permission appears unrelated to checking or managing a loan, I would not grant it automatically. On Android, permissions can be reviewed and adjusted through the device settings, so I would use those controls when I want to limit access. If a feature stops working after a permission is denied, that gives me useful information about the feature’s dependency, but I would still decide based on whether the convenience is worth the access.
I would also avoid sending sensitive loan details through ordinary text messages or screenshots unless there is a clear reason and a trusted recipient. A screenshot can contain more information than intended, including account identifiers or dates. For a routine question, using the app’s visible account or support path is usually more orderly than creating a separate copy of the information on my phone.
Privacy choices are not a one-time decision. After an update, I would glance at the app’s permissions and notification behavior again, especially because the current version may change how a screen works. The app was released on April 2, 2024, and its version history can move on after installation; I would therefore treat updates as a reason to review the experience rather than assuming every setting remains exactly where I left it.
Where user agency matters most
For me, user control in a loan app means being able to understand what I am viewing, choose when to act, and stop before confirming something consequential. I would not rush through a payment-related screen simply because a due date is approaching. Instead, I would verify the account, read the amount and timing carefully, and keep a record of any confirmation that matters to my budget.
A useful personal workflow is to check the app at a calm time, not in the final minutes before a payment deadline. I can then compare the information with my bank balance, note any important dates, and resolve questions while there is still time to seek help. This is one of the less obvious benefits of a dedicated account app: it can make a recurring responsibility easier to remember, but only if I build a deliberate routine around it.
I would also keep the app’s role separate from my decision-making. Seeing a loan account in a clean mobile interface can create a feeling of control, but it does not automatically make the underlying borrowing affordable. I would use a spreadsheet, notes app, or bank budget view for the wider calculation and use Together Loans for the account-specific part.
That approach is particularly helpful for anyone managing irregular income. A person paid weekly or working variable hours may need to check the loan account while planning several smaller cash-flow decisions. The app can be convenient for the account check, but the final decision should come from a broader view of upcoming income and essential expenses.
A realistic everyday scenario
Imagine I am planning the month on a Sunday evening and notice that a loan-related payment needs to be accounted for. Instead of searching through messages, I open Together Loans, sign in carefully, and review the account information. I then compare it with my household budget and bank balance, write the relevant detail in my monthly notes, and close the app.
If the information is clear, the task takes only a short part of the evening. If something looks different from what I expected, I do not guess or repeat an action just to make the screen change. I save the relevant confirmation, check the wording again, and use the available account-support route to clarify the issue. The app is useful here because it gives me a focused starting point, not because it removes the need for judgment.
For someone who tends to forget loan administration, that routine may be more valuable than any extra feature. For someone who already receives clear reminders and manages several accounts through a trusted banking app, the additional installation may not add enough convenience to justify another login on the phone.
How it compares with usual alternatives
The closest alternative is often the lender’s mobile website. A browser can be perfectly adequate, especially for someone who rarely checks the account. It may also be preferable if I do not want another app installed or if I use different devices. The dedicated app becomes more appealing when I want a repeatable, phone-first route to the same loan relationship.
A general budgeting app serves a different purpose. It can help me see whether a loan payment fits alongside other spending, while Together Loans is better suited to the loan account itself. I would not choose one as a complete substitute for the other. In practice, the most sensible combination can be a budgeting tool for the household view and this app for the lender-specific view.
A bank app may also show scheduled payments or outgoing transactions, but it may not provide the same account context as a lender’s own service. Conversely, a bank app can be better for checking whether the money is available across my accounts. The trade-off is clear: Together Loans offers focus, while a bank or budgeting app offers broader financial context.
People comparing lenders should skip this app as their main research tool. It is not the right place to make a neutral comparison between borrowing products. I would first decide whether the loan is appropriate, read the terms carefully, and then use the app only if I become a Together Loans customer and want that account-management convenience.
Who will benefit and who should pass
I think the app is best for existing Together Loans customers who prefer checking a loan account from a phone. It may also suit people who want a dedicated place for loan administration rather than mixing it with everyday banking screens. The free download removes a financial barrier to trying it, and the Everyone rating means it is presented for a broad audience.
I would be more cautious about recommending it to someone who expects credit education, debt counseling, multi-lender tracking, or detailed spending analysis. Those needs call for different tools and possibly professional guidance. A person uncomfortable with mobile account management may also prefer the lender’s other available contact methods, particularly for complicated questions.
It is worth remembering that a strong rating does not guarantee a frictionless experience for every account. The app has 272 written reviews, and individual experiences can depend on the user’s account situation, device, sign-in details, and the task being attempted. I would treat the rating as a useful signal of overall reception, not as a promise that every payment or support issue will be resolved immediately.
My cautious verdict
Together Loans succeeds when I judge it as a focused finance companion. Its purpose is easy to understand, its free availability makes it straightforward to try, and its value comes from reducing the effort involved in checking and managing a Together Loans account from an Android phone. The developer identity, current version, and visible account context give me sensible starting points for a careful trust check.
My recommendation comes with boundaries. I would use it with a secure device, review permissions and notifications, read every confirmation screen, and keep a separate budget for the wider affordability picture. I would also avoid assuming that a convenient app replaces the loan agreement, independent financial judgment, or direct clarification when something looks wrong.
The best reason to install Together Loans is simple: it gives an existing customer a focused place to handle a specific loan relationship. If that is exactly what I need, it is a practical addition to my phone. If I want a complete view of my money or a way to compare borrowing choices, I would choose a broader financial tool instead and keep this app, if needed, for the narrower account tasks it is built to support.
Pros
- Quickly compare loan options from multiple lenders in one place.
- Simple application process with clear steps for borrowers.
- May help users with limited credit explore available offers.
- Convenient access to loan information from a mobile device.
- No need to visit multiple lender websites individually.
Cons
- Approval and rates depend on third-party lenders, not the app itself.
- Loan offers may include high APRs, especially for weaker credit profiles.
- Submitting an application may trigger marketing calls or messages.
- Availability and terms can vary by location and personal information.
- Some lenders may charge origination or other additional fees.
FAQs for Together Loans
What is Together Loans, and what does the app offer?
Together Loans is a digital lending service designed to help users explore borrowing options and manage loan-related requests online. Depending on your location and eligibility, the platform may provide access to personal finance products, application guidance, repayment information, and customer support. Available services, loan amounts, interest rates, and terms can vary, so review the official offer carefully before accepting any agreement.
Who can apply for a loan through Together Loans?
Eligibility requirements depend on the specific Together Loans service, the applicant’s country, and the lending partners involved. Applicants may need to meet minimum age requirements, provide valid identification, demonstrate a regular source of income, and have an active bank account. Approval is not guaranteed, and submitting an application may involve credit, affordability, identity, or fraud checks.
Are Together Loans applications free, and what costs should I check?
Starting an application may be free, but borrowing money can involve interest, arrangement fees, late-payment charges, broker fees, or other costs depending on the product and provider. Before proceeding, check the representative APR, total amount repayable, repayment schedule, and consequences of missed payments. Never rely only on an advertised rate, because your personal offer may differ.
How long does it take to receive a decision or funds from Together Loans?
Processing times can vary according to the type of loan, the information supplied, verification requirements, and the lender handling the application. Some decisions may be provided quickly, while additional documentation or manual checks can cause delays. Even after approval, funds may arrive according to the lender’s banking schedule. Always confirm the expected timeline in the final agreement.
Is Together Loans safe to use, and what should I do before applying?
Use Together Loans only through its official website or verified application listing, and check that the service is authorized to operate in your region. Read the privacy policy and loan agreement before sharing personal or financial details. Avoid services requesting upfront payments through unusual methods or promising guaranteed approval, and contact official support if an offer or message appears suspicious.

Together Loans
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@togetherloans.com, visit https://togetherloans.com, or review their https://www.transformcredit.com/privacy-policy.










